

Many people hear the word insurance and think of long forms, big companies and payments they may never see again. Others buy policies without understanding the cover. They discover the limits only when they need help.
Treat insurance as an answer to a practical question: what could happen to my health, income, vehicle, home or business that I would struggle to pay for tomorrow?
Someone with a small income may not protect everything at once. That does not make insurance useless. It means the person should start with the risk that could cause the greatest damage. 
What insurance really does
Insurance creates a contract between you and an insurer. You pay a premium, usually monthly, quarterly or annually. The company then agrees to pay a stated benefit or cover a particular loss if a specified event occurs during the policy period.
Three words matter: stated, covered and specified. A policy will not pay for every problem. It will pay only according to its terms.
Your premium keeps the policy active. You make a claim after a covered event. The sum insured or benefit limit sets the highest amount the insurer can pay. An exclusion names a situation the policy does not cover. Some policies also set an excess or deductible. You pay that part of the loss yourself.
These terms can prevent a common mistake: assuming an insurance certificate means the insurer will refund every loss in full.
The main types of cover people may need
Health, life and personal protection
Health insurance helps you pay for medical care under an approved plan. Before joining, ask which hospitals you can use, which drugs and tests the plan covers, whether a waiting period applies, what co-payment you may make and how the plan handles emergencies. A cheap plan may disappoint if the nearest hospital or the treatment your family needs falls outside the network.
Life insurance supports dependants. It can pay a named beneficiary after the insured person dies, depending on the policy. The cover may matter to a parent who pays school fees, a spouse who supports a household or anyone whose income keeps a family business running. Do not assume that every life policy also works as a savings or investment plan. Check the contract.
Personal accident insurance can pay a benefit when an accident causes death, permanent disability or another listed injury. It does not replace health insurance, and it may not pay for ordinary illness.
Vehicles, homes and small businesses
Motor insurance helps you manage liabilities connected with a vehicle. Nigerian law requires third-party motor insurance, but third-party cover generally pays for injury or property damage that the insured vehicle causes to other people. It does not normally pay for damage to the owner’s own car. Comprehensive cover offers wider protection, but it still carries limits, exclusions and conditions. Vehicle owners should verify the certificate and confirm that the insurer holds the right licence.
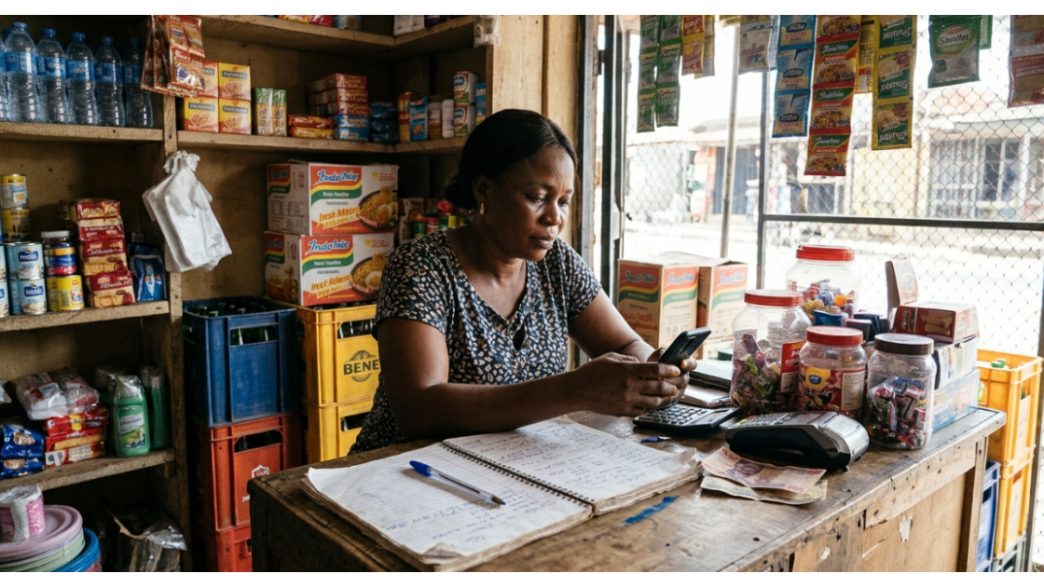
Property and business insurance can protect a building, household contents, stock, equipment or listed risks such as fire, theft and accidental damage. A landlord’s building policy does not automatically protect a tenant’s belongings. A trader should ask whether the policy covers the actual stock and equipment in the business, rather than only the shop structure.
Microinsurance offers simple products to people with lower or irregular incomes. These products may cost less, but they may also offer narrower benefits and lower limits. Ask for the written policy and confirm that the provider has a licence.
YOU MIGHT ALSO LIKE: Google Unveils AI Max Tools to Help Nigerian Businesses Ahead of Black Friday
How to choose an insurance policy when money is tight
Do not start with the policy an agent advertises. Start by listing the risks that would be hardest to survive.
Your household may fear a serious illness. Another family may depend on one income earner, while a commercial driver may worry about liability after a road crash. A petty trader may face the greatest danger from losing all the stock in a fire.
After you identify the main risk, take these steps:
- Start with the loss that could push the household into debt. Insurance should solve a problem, not create another one.
- Check what the law requires and what remains optional. Nigerian law requires vehicle owners to carry third-party motor cover. Broader cover may depend on the vehicle’s value and the owner’s ability to pay.
- Choose a premium you can maintain. If you stop paying, the policy may lapse before you need it. Ask whether the company accepts monthly payments, what happens after a missed payment and how renewal works.
- Insure what matters, not what sounds impressive. A policy with many benefits may still offer poor value if its exclusions are wide or its limits are too low for the risk.
- Review the cover when life changes. Marriage, a new child, a new vehicle, a new business location or a major income change may require more or different protection.
No one needs to start with several policies. Begin with one modest cover and build gradually. Pair insurance with basic precautions and emergency savings; do not treat it as a replacement for either one.
Questions to ask before paying for an insurance policy
Ask the agent or company to explain these points in plain language:
- What exactly does the policy cover?
- What does it exclude?
- What benefit limit applies?
- How much is the premium, and when must you pay it?
- Does the policy include a waiting period, excess or co-payment?
- Who can make a claim, and which documents will the company request?
- How soon must you report an accident, illness or loss?
- Which hospitals, workshops, assessors or other service providers can you use?
- What happens if you cancel the policy or miss a renewal?
- Who receives a life benefit, and how will your family learn about the policy?
The company should give you the policy document, certificate, schedule, payment receipt and claims contact. Do not treat a promise from a phone call or WhatsApp message as a substitute for written terms.
Verify the provider before you pay, and use an official payment channel. In Nigeria, the National Insurance Commission, or NAICOM, publishes information about licensed insurers, brokers and other operators. If you have a complaint, use the insurer’s complaint process first. Keep copies of every letter, receipt and message before you take the matter to the regulator.
Health-plan customers should also confirm whether the plan comes from the National Health Insurance Authority, a state health insurance agency or an approved private provider. They should check the current list of participating hospitals before they enrol.
SEE ASLO: The Nigerian Emergency Folder Every Household Should Have
What to do when a loss occurs
Report the event as soon as possible and follow the policy’s instructions. A motorist involved in a crash may need photographs, a police report, vehicle documents and repair estimates. A health-plan member may need to visit an approved hospital or obtain prior authorisation. A family making a life claim may need the policy documents, proof of death and proof of its relationship to the policyholder.
Keep your evidence – Requirements vary, so do not guess. Keep damaged property, photographs, receipts, medical records and other evidence when it is safe to do so. Ask the insurer what to do before you accept a settlement or throw away important evidence.
When a claim stalls or the insurer rejects it, ask for the reason in writing and compare that reason with the policy. A disagreement does not prove that the insurer acted unfairly. In the same way, a rejection does not always end the matter. Use the policy and your documents to understand the decision.
The simple test
Insurance does not signal wealth. It helps people share a risk before that risk becomes a crisis.
Before you buy, ask three questions: What loss do I want to protect against? Can I keep paying for this cover? What must I do to make a valid claim?
Clear answers put you in a better position to choose. If the answers remain unclear, pause, compare another policy and ask more questions. The cheapest policy is not always the best one, and the most expensive policy is not automatically better.
The most useful insurance is the cover you understand before trouble comes.
Frequently Asked Questions
No. People with different incomes can choose different levels and types of cover. The important question is whether the premium is affordable and whether the policy protects a real risk.
A premium is the money paid to keep the policy active. A claim is the request made after a covered event occurs.
Not usually. Third-party cover generally addresses liability to other people. A vehicle owner must check the policy terms to know whether damage to their own vehicle is covered.
Ask for the reason in writing, compare it with the policy terms, use the insurer’s complaint process and keep copies of all documents. If the matter remains unresolved, escalate through the relevant regulator’s complaint channel.
Microinsurance refers to simplified insurance products designed to be more accessible to low-income and underserved customers. The lower cost may come with narrower benefits or limits, so the buyer still needs to read the terms.
READ ALSO: NELFUND 2026/2027 Student Loan: Eligibility, Requirements and How to Apply

About The Author