

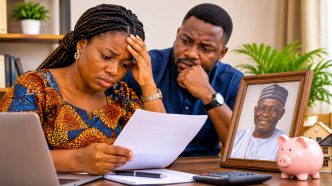
Have you ever stopped to ask yourself the question, “How can my spouse access my money if I die?”. Yes, thinking about death is difficult, but it is hard enough without your spouse having to spend the next several months moving between bank branches, lawyers and government offices just to find out what happened to the money you both worked for.
But that is a reality many families discover after losing a loved one. A surviving husband or wife may know their partner had money in several bank accounts, investments or savings platforms. Yet, they find themselves unable to withdraw a single naira because the account belonged exclusively to the deceased.
This is a situation many people never think about until they are forced to confront it. And contrary to popular opinion, being married to the account holder, being their child or being listed as their next of kin does not automatically give you the legal right to withdraw the money. 
The process depends on how the account was structured and whether the deceased left a valid will. It can also depend on the legal authority the surviving family member can obtain.
So, if you’re wondering how your spouse can access your money if you die, here’s how it works in Nigeria. This is what you can do to make things easier for the people you leave behind.
Why can’t your spouse simply withdraw your money?
When someone dies, the money in their personal bank accounts generally becomes part of their estate. The bank cannot simply hand the money to whoever shows up with a death certificate and a convincing explanation of how they were married for 30 years.
Banks must protect the deceased customer’s assets and ensure they release money to the people legally authorised to administer the estate.
This means your spouse may need to obtain a court-issued grant before accessing money held in your sole-name accounts. Even if they know your PIN, have your ATM card or can access your banking app, attempting to withdraw money after your death could create legal problems.
And no, putting someone’s name down as your next of kin when opening an account does not magically turn them into the owner of the money.
ALSO SEE: 2 AM Emergency in Nigeria: 9 Steps To Prepare for a Midnight Crisis
How can my spouse access my money if I die in Nigeria?
The process generally depends on whether the deceased left a valid will.
1. If the deceased left a will, apply for Grant of Probate
A will allows someone to specify how they want their assets distributed after death and name the people responsible for carrying out those instructions.
These people are called executors. However, being named an executor in a will does not, on its own, mean you can walk into a bank and start withdrawing money. The executor generally needs to obtain a Grant of Probate from the appropriate Probate Registry.
The grant gives the executor legal authority to administer the estate, including dealing with the deceased’s bank accounts and other assets.
Once probate is obtained, the executor presents the grant and the bank’s required documentation to begin the process of accessing or transferring the money.
2. If there is no will, apply for Letters of Administration
If someone dies without a valid will, the estate is described as intestate.
In this situation, eligible relatives can apply to the Probate Registry for Letters of Administration. This legally authorises appointed administrators to manage the deceased’s estate. A surviving spouse may be eligible to apply, often alongside other eligible relatives, depending on the applicable state law and circumstances.
The process may require identification documents, the death certificate, photographs, application forms, information about the estate and other supporting documents. The exact requirements differ between states.
In Lagos, the Probate Registry provides information and application services for both probate and Letters of Administration through its e-Probate portal.
What documents will the bank ask for?
Once the family obtains the appropriate grant, the bank will usually require documents to verify the deceased, the legal representatives and their authority.
Depending on the bank and circumstances, these may include:
- The deceased person’s death certificate.
- Grant of Probate or Letters of Administration.
- Valid identification documents of the executor or administrator.
- Bank account details or other information identifying the account.
- Additional forms, affidavits or documentation requested by the bank.
The bank may also verify the grant before releasing funds. In some cases, it may direct the executor or administrator to open an estate account into which the deceased’s balances can be transferred before distribution to beneficiaries.
What if you are listed as the next of kin?
This is where many families get caught out.
Being listed as the next of kin on someone’s bank account does not automatically give you ownership of their funds or the authority to withdraw them after death. The designation generally helps the bank identify and contact a relative in an emergency. It is not the same as being named as an executor in a will, an administrator under a grant or a beneficiary of an asset with a valid beneficiary designation.
So, if your husband or wife listed you as their next of kin, that may help the bank contact you after their death. However, it does not automatically bypass the probate process.
SEE ALSO: Hot Take: These Weird Nigerian Food Combinations Should Attract Jail Time
What happens to joint accounts, insurance and pensions?
Joint accounts may offer easier access to money. However, do not assume every joint account automatically transfers its entire balance to the surviving holder. The account mandate, bank terms and applicable law matter, and the bank may restrict access after learning of a death.
Life insurance policies and pension benefits may follow different procedures from ordinary bank accounts. Where a valid beneficiary or nominee has been designated, the provider may have a separate claims process for paying the benefit. The claimant should contact the insurer or pension administrator and confirm its documentation requirements.
This is one reason it is worth checking your financial arrangements while you are still alive, rather than leaving your spouse to discover how they work during a period of grief.
How to make it easier for your spouse to access your money if you die
You do not need to be wealthy to plan for what happens to your money. Even if your entire financial empire consists of a salary account, a savings account and an investment you keep forgetting about, a little preparation can save your family considerable stress.
Here are some things you can do:
- Write a valid will: Clearly state how you want your assets distributed and appoint executors you trust.
- Keep an updated record of your finances: List your banks, accounts, investments, insurance policies and pension providers somewhere secure that your spouse or executor can locate.
- Review joint accounts: Understand the account mandate and ask your bank what happens if one account holder dies.
- Update beneficiary details: Check the beneficiaries or nominees on insurance policies, pensions and other financial products where applicable.
- Tell your spouse where important documents are: They do not necessarily need your passwords. However, they should know where to find your financial records and estate-planning documents.
The money conversation most couples keep postponing
Nobody enjoys discussing death. It is much easier to discuss a holiday, a new car or what to eat for dinner. But planning ahead is not morbid. It is one of the more practical things you can do for someone you love.
Your spouse should not have to become a detective, a lawyer and a professional queue-survivor simply to figure out where you kept your savings.
A valid will, organised financial records and a clear understanding of how your accounts work can make a difficult process considerably easier. And if you have not sorted any of that out yet, perhaps this is the nudge you need to stop postponing it.
ALSO READ: What to Do If You Accidentally Transfer Money to the Wrong Bank Account in Nigeria

About The Author